


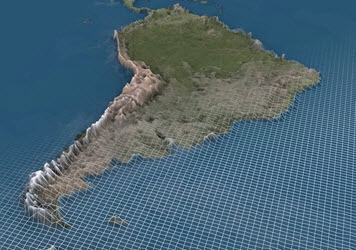
Corn The corn market situation is similar to the past few weeks with the soybean harvest accelerating and exceeding that of corn. Consequently, the arrival of corn to ports is slowing and seems insufficient relative to the present vessel lineup. Exporters who needed corn at the ports urgently were forced to pay up in the local market, even with the weaker CBOT, which left very high replacement values. Corn is still in demand from all destinations and for all origins. Argentine corn has strong demand from Southeast Asia, North Africa, and some Latin American countries as well. There is active and fresh demand appearing along with some short covering as well. Exporters have already booked large programs for May/June shipments. They st...


 Key Takeaways: Dry bulk markets remain mixed with Capesize vessels seeing continued pressure from weaker demand while fixtures and rate strength gradually increases towards the smaller vessel classes. Tanker markets are pulling back from their recent highs as tonnage moves out of the Mid...

 The Trump import plan for 300,000 MT of beef supplies used for ground beef, i.e., lean trim, from September through November has, according to Secretary Brooke Rollins, brought some relief to beef prices. The Executive Order states that the Secretary of Agriculture will analyze and review the m...
 Key Takeaways: Texas illustrates the assumptions underlying the 2025 FMMO reform; Idaho exposes their limitations. The Southwest order blend (roughly 27 percent Class I, 32 percent Class III and 31 percent Class IV) exposes Texas producers to every lever USDA adjusted, with a near-neutral proj...

From WPI Consulting
Forecasting developments in production agriculture
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.