
The Market Oilseed markets have been volatile again this week amid the tariff-induced meltdown in macroeconomic and ag markets and Wednesday’s massive reversal and rally in the same markets. The net result of this is that soy complex futures are largely little changed – especially in the context of the recent volatility – from last week. Soybeans and soymeal are up fractionally as hope is building for some agreement with China while soyoil is lower than last week due to the collapse in energy markets. The soy crush is slightly lower, consequently, with the oilshare of the margin falling 1.3 percentage points to 43.7 percent. The May board crush margin (that processing margin implied by May futures contracts) is down...


 Beef packer margins deteriorated to $156.75/head last week, down $46.05 from the prior week as fed cattle prices strengthened while gains in the Choice cutout were comparatively modest. The Choice cutout increased...


 What You Need to Know Today: Oil prices moved higher early Monday before giving back some of their gains after drone attacks forced the shutdown of Saudi Arabia’s East-West Pipeline, a critical route for bypassing constrained shipping through the Strait of Hormuz. The disruption puts rou...
 Key Takeaways: Expected returns to production for U.S. cow-calf producers have shifted lower from prior forecasts as cattle values fall and feed costs rise. Producer revenues are forecast 1 percent below our August outlook and will be 1.2 percent below 2025 levels. Feed costs have lessen...

From WPI Consulting
Forecasting developments in production agriculture
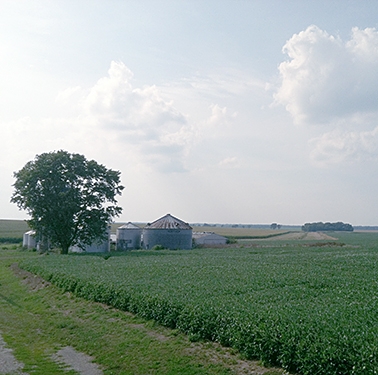
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.