


THE OPEN Nov beans: 3 1/2 higher Dec meal: 1.40 lower December soyoil: 60 pts higher December corn: 2 3/4 higher December wheat: 1 lower The markets opened as called but prices quickly drove higher as the beginning of the week brings with it warmer and drier temperatures. Short-covering, bargain hunting, and pricing activity drove prices upward, with soyoil futures having the largest gains. Canola prices remained locked limit on forecasts for continuing hot and dry weather in Canada's growing regions. At 10:00 export inspections were released as follows: beans: 200,933 mt vs. 208,136 mt week ago (vs. an expected 100-300,000 mt) corn: 993,974 mt vs. 1,236,248 mt...


 What You Need to Know Today: Cattle futures extended their sharp selloff Friday as weakening cash cattle prices, deteriorating feedlot profitability, and reduced packer demand continued to weigh on the market. The inability of futures to sustain a rally following last week's bullish Cattle on...


 As predicted, the Federal Reserve held rates steady at the last meeting before the midterm elections, likely in part because of the election (see WPI 19 October and 22 September). The decision comes at the tail end of a midterm election cycle that has been marked by the two parties campaigning...

 Key Takeaways: WPI’s new EU rapeseed crushing margin models point to weaker processing returns over the next four months due to higher rapeseed procurement costs and weaker product values. Statistical forecasts call for German crushing margins to decline from €181/MT to €...

From WPI Consulting
Forecasting developments in production agriculture
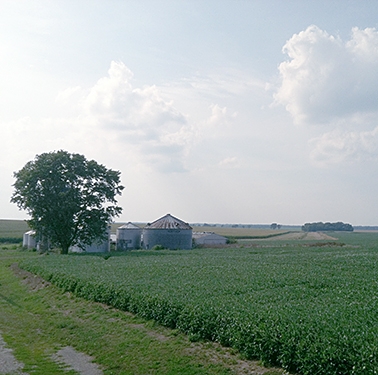
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.