The second Trump administration has roiled global markets in just its first few weeks in office, with some of the biggest impacts coming from the application of tariffs against major trading partners. These tariffs have, as expected, been met with retaliation from Canada, Mexico, and China. Further complicating the global trade outlook has been China’s move to retaliate against tariffs from other non-U.S. trading partners, most notably Canada. As a major importer (and often the largest for a given product), China’s retaliatory tariffs against two major suppliers are of key interest to WPI readers. Some of these tariffs have been highly publicized and target markets with which WPI readers are already familiar (e.g., soybean...


 Beef packer margins deteriorated to $156.75/head last week, down $46.05 from the prior week as fed cattle prices strengthened while gains in the Choice cutout were comparatively modest. The Choice cutout increased...


 What You Need to Know Today: Oil prices moved higher early Monday before giving back some of their gains after drone attacks forced the shutdown of Saudi Arabia’s East-West Pipeline, a critical route for bypassing constrained shipping through the Strait of Hormuz. The disruption puts rou...
 Key Takeaways: Expected returns to production for U.S. cow-calf producers have shifted lower from prior forecasts as cattle values fall and feed costs rise. Producer revenues are forecast 1 percent below our August outlook and will be 1.2 percent below 2025 levels. Feed costs have lessen...

From WPI Consulting
Forecasting developments in production agriculture
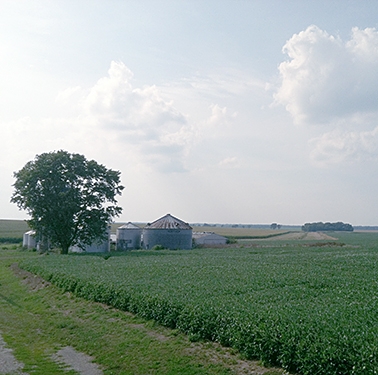
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.