


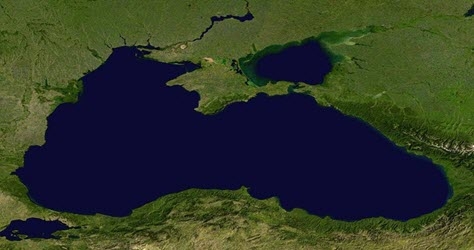
Russian Grain Markets 18–22 September 2023 The Russian bear continued marching over all grains in European Russia without exception. The Asian part of Russia was more stable but sooner or later the bear will reach that part of the country as well as the domestic crop is huge and far exceeds Russia’s needs. The export market remains unmistakably bearish and part of the reason beyond global bearish sentiments is the lack of international players on the market to force competition. Some traders believe that grain prices in the ports have already reached their bottom levels, however export duties and higher input costs for farmers are scaring the bull off. At the beginning of the marketing year, the wheat export duty...


 What You Need to Know Today: Cattle futures extended their sharp selloff Friday as weakening cash cattle prices, deteriorating feedlot profitability, and reduced packer demand continued to weigh on the market. The inability of futures to sustain a rally following last week's bullish Cattle on...

 Key Takeaways: WPI’s new EU rapeseed crushing margin models point to weaker processing returns over the next four months due to higher rapeseed procurement costs and weaker product values. Statistical forecasts call for German crushing margins to decline from €181/MT to €...
 Key Takeaways: The tariff burden rose sharply in 2025 and 2026: the effective rate on imports in HTS Chapters 1–24 increased from 1.53 percent in 2024 to 6.11 percent in 2025, before averaging 5.68 percent in January–August 2026. Headline rates tell only part of the story: exemptio...

From WPI Consulting
Forecasting developments in production agriculture
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.