
This week’s WASDE report from USDA was considered slightly bullish for prices, although that certainly wasn’t apparent by the market’s action during the past few trading sessions. U.S. corn and soybean ending supplies were reduced. World demand remains very strong, but crop problems stretching from the Black Sea to Australia are causing world production to slip. The one aspect of the report that has raised questions is the U.S. winter wheat production estimate, and June can be a difficult month for assessing that crop. Many of the variables at play will be resolved by the time of the July report, however. Chief among these is the “harvested” acreage number, which is critical to any final production estimate. T...



 What You Need to Know Today: New World screwworm is back in the headlines after new cases were found in a hunter-harvested elk in Texas and a beef cow in New Mexico. The detection in wildlife could further complicate containment efforts, as implementing effective biosecurity measures is consid...

 Cattle on Feed Expectations USDA’s monthly Cattle on Feed report that will show cattle inventory statistics as of 1 October will be released tomorrow, 23 October. Analysts’ pre-report consensus estimates are for the total inventory on feed to be 100.3 percent of last year, which imp...

 Key Takeaways: Dry bulk markets remain mixed with Capesize rates turning around from their recent weakness and posting solid gains on improved Chinese demand. Panamax vessels, on the other hand, saw rates decline amid greater tonnage availability in the South Atlantic and falling U.S. Gu...

From WPI Consulting
Infrastructure investment due diligence
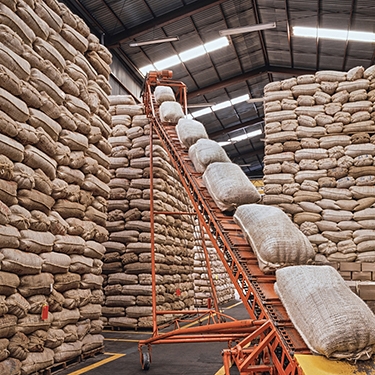
On behalf of a Canadian oilseed processer WPI's team provided market analysis, econometric modeling and financial due diligence in support of a $24 million-dollar investment in a Ukrainian crush plant. Consistent with WPI's findings, local production to supply the plant and the facility's output have expanded exponentially since the investment. WPI has conducted parallel work on behalf of U.S., South American and European clients, both private and public, in the agri-food space.