


The CBOT was mixed for the day with wheat futures sinking lower after the HRW and SRW growing regions received favorable rains Wednesday and early Thursday. That, combined with export pressure from Russia and the Black Sea countries, put wheat on the defensive with funds emerging as net sellers again. The pressure in wheat spilled over into corn and pushed the spot December contract lower, though bear spreading lifted deferred markets. Strong export sales and a rally in soyoil sent the soybean market higher, though the charts still look bearish. The markets are now largely focused on export trends and prices, weather for the Northern Hemisphere winter wheat crops, and rains in Argentina and Brazil. Seasonally, futures are approaching t...


 What You Need to Know Today: New World screwworm is back in the headlines after new cases were found in a hunter-harvested elk in Texas and a beef cow in New Mexico. The detection in wildlife could further complicate containment efforts, as implementing effective biosecurity measures is consid...

 Cattle on Feed Expectations USDA’s monthly Cattle on Feed report that will show cattle inventory statistics as of 1 October will be released tomorrow, 23 October. Analysts’ pre-report consensus estimates are for the total inventory on feed to be 100.3 percent of last year, which imp...

 Key Takeaways: Dry bulk markets remain mixed with Capesize rates turning around from their recent weakness and posting solid gains on improved Chinese demand. Panamax vessels, on the other hand, saw rates decline amid greater tonnage availability in the South Atlantic and falling U.S. Gu...

From WPI Consulting
Forecasting developments in production agriculture
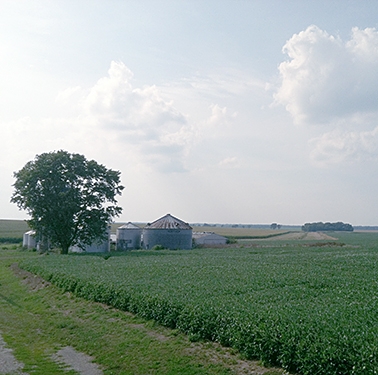
On behalf of a private U.S. agricultural technology provider, WPI’s team generated an econometric model to forecast the movement of concentrated corn production north and west from the traditional U.S. Corn Belt. WPI’s model has subsequently provided quantitative support to a multi-million-dollar investment into short-season corn variety development. WPI’s methodology included a series of interviews with regional grain elevators and seed consultants. Emphasizing outreach and communication with stakeholders who possess intimate sectoral knowledge – on-the-ground insights – is a regular component of WPI’s methodologies, made possible by WPI’s ever-growing network of industry contacts.